04 — Tax Litigation & Dispute Resolution

Direct & Indirect Tax Litigation

Careful examination of facts, applicable legal provisions, and judicial precedents. Relentless advocacy across departmental proceedings, CIT(Appeals), ITAT, GST Appellate Authorities, and High Courts.

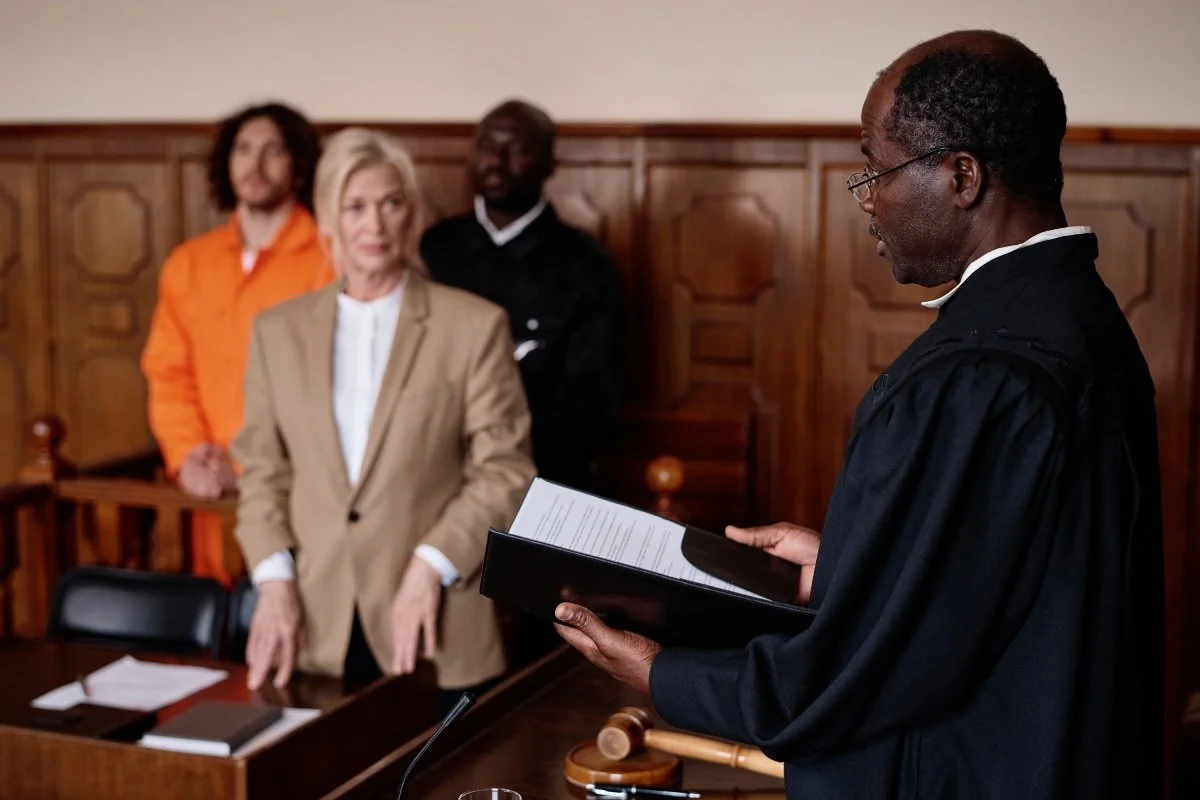
Tax Litigation Senior Advocates representing clients before tribunals
Strategic Defense

Protecting Your Interests Across Tax Controversies

Tax disputes arising under the Income-tax Act and Goods and Services Tax laws often involve contentious statutory interpretations, high-stake financial liabilities, and strict limitation deadlines. At INDCORPUSCA, our dedicated direct and indirect tax litigation practice represents clients across the entire dispute lifecycle.

From formulating robust responses to departmental notices and assisting during scrutiny or search proceedings to preparing evidentiary paper-books and arguing before Appellate Commissioners, Tribunals, and Courts, we combine meticulous factual scrutiny with authoritative judicial precedents to secure optimal remedies.
Practice Areas

Direct & Indirect Tax Litigation Services

Comprehensive legal representation tailored to protect your financial interests, challenge arbitrary assessments, and pursue statutory remedies.

Assessment & Reassessment Proceedings

Complete assistance in assessment and reassessment proceedings, including matters arising from Section 148, 148A, 143(2) scrutiny notices, questionnaires, and proposed additions or disallowances before the National Faceless Assessment Centre.

Tax Notices & Departmental Proceedings

Advising and assisting in responding to show-cause notices, summons, and communications under the Income-tax Act. We examine issues raised, analyse legal provisions, and prepare comprehensive representations with supporting documentation.

Additions & Disallowances Disputes

Representation in disputes relating to additions and disallowances made during assessment, including income recognition, business expenditure, exemptions, deductions, unexplained cash credits (Sec 68), and investments.

Search, Seizure & Survey Matters

Expert advisory in proceedings arising from search & seizure (Section 132) and survey (Section 133A) actions. We examine the factual matrix, prepare legal submissions, and represent before authorities and appellate forums.

Penalty & Prosecution Defense

Evaluating statutory criteria and presenting robust factual grounds in defence against penalty notices under Section 270A/271(1)(c). Assistance and compounding remedies for potential or initiated prosecution proceedings.

Appeals before CIT(A) & ITAT

Drafting statutory appeals (Form 35/36), formulating Grounds of Appeal, compiling comprehensive paper-books, filing additional evidence under Rule 46A, and representing clients before Commissioner (Appeals) and the ITAT.

Stay of Demand, High Court & Supreme Court

Filing stay of demand petitions under Section 220(6) against coercive recovery, Section 154 rectifications, Section 264 revisions, and pursuing substantial questions of law or writ petitions before High Courts and Supreme Court.

GST Notices & Adjudication Proceedings

Assisting clients in responding to GST notices, scrutiny proceedings (ASMT-10), and show-cause notices (DRC-01/01A), including drafting factual and legal replies and providing effective representation before adjudicating authorities.

Input Tax Credit & Refund Disputes

Advising and representing in disputes concerning ITC eligibility, documentation, 2B-3B mismatches, availment, reversal, export refund rejections, inverted duty structures, and concessional rate interpretations under GST laws.

Customs, E-Way Bill & Appellate Remedies

Defending e-way bill transit detentions, interest/penalties, customs classification and valuation disputes, legacy excise/service tax matters, and statutory appeals before the GST Appellate Authority and Tribunal.

Our Methodology

A Rigorous Litigation Process

Our structured litigation workflow combines forensic factual analysis with established legal principles to safeguard your interests and achieve favorable resolutions.

Facing an Urgent Notice?

Review our Litigation FAQ or book an immediate case briefing.

Step 1

Factual Examination & DIN Verification

Detailed scrutiny of the impugned notice or assessment order, verification of the Document Identification Number (DIN), and audit of underlying books of accounts.

Step 2

Legal Research & Precedent Mapping

Deep-dive statutory interpretation and identification of binding judicial precedents from High Courts, Supreme Court, and jurisdictional benches of ITAT.

Step 3

Submission Drafting & Bench Advocacy

Preparation of comprehensive written submissions, paper-books, evidence compilation, and rigorous oral or virtual representation before tax authorities and tribunals.

Step 4

Stay of Demand, Orders & Appeal Follow-Up

Securing stay of coercive tax demand under Section 220(6), monitoring appellate order effect, refund issuance, and determining subsequent appellate avenues.

15 +

Years Legal Experience

1,200 +

Notices & SCNs Resolved

350 +

Appellate Appeals Argued

98 %

Client Satisfaction

Professional Support for Every Stage of Business

Business Registration Services
GST Registration & Compliance
Income Tax Return & Planning
Accounting & Bookkeeping Services
Corporate Compliance & Secretarial
Representation Tiers

Transparent Litigation Retainers

Defined procedural stages with clear milestone deliverables. No hidden litigation overheads or unexpected costs.

Notice Advisory & Reply

₹7,500 / notice

For preliminary department queries, Section 142(1) inquiries, and GST DRC-01A intimations.

  • Statutory Notice & DIN Validation
  • Fact Verification against Books of Accounts
  • Comprehensive Written Rebuttal Drafting
  • Reconciliation & Evidentiary Annexures
  • Digital Portal Upload & Receipt Archival
  • Single Level Departmental Follow-up

CIT(A) & ITAT Appeals

₹35,000 / appeal starting

Statutory Form 35/36 appeals, compilation of paper-book, and Senior Counsel advocacy.

  • Grounds of Appeal & Statement of Facts
  • Additional Evidence Petitions (Rule 46A)
  • Preparation of Comprehensive Paper-Book
  • Oral Arguments before Bench / CIT(A)
  • Condonation of Delay Applications
  • Appellate Order Effect Implementation
Client Feedback

"When we received a Section 148 reassessment notice proposing huge additions for unexplained credits, INDCORPUSCA's litigation team immediately challenged the jurisdictional basis. Their factual paper-book and High Court citations resulted in the entire addition being quashed at the CIT(A) stage."

"Our business faced a ₹48 lakh GST demand under DRC-01 citing blocked input tax credit under Section 17(5). INDCORPUSCA represented us before the adjudicating authority with thorough vendor reconciliations and legal rebuttals, securing a full drop of proceedings without penalty."

"The team at INDCORPUSCA handled our stay of demand petition under Section 220(6) with extreme urgency when our bank accounts were facing attachment. Their prompt representation before the Principal Commissioner provided our company complete breathing space."

Need Urgent Counsel?

Defend Your Case with Experienced Counsel

Do not let arbitrary tax additions compromise your hard-earned capital. Retain our senior tax advocates and Chartered Accountants for immediate case defense and statutory relief.

Schedule Confidential Case Review
Tax Litigation FAQ

Answers to Common Tax Dispute Questions

Do not ignore it. Section 148 relates to reopening of assessment where income has allegedly escaped assessment. First, verify the mandatory Document Identification Number (DIN). Second, verify whether statutory pre-inquiry under Section 148A was conducted. Third, file the return of income under protest within the stipulated timeframe and formally request the "reasons to believe" and sanction approvals to challenge jurisdictional validity.

Filing an appeal does not automatically stay tax recovery. You must file a formal Stay Petition under Section 220(6) before the Assessing Officer and Commissioner. Under CBDT circulars, depositing 20% of the disputed demand typically stays recovery of the remaining 80% pending disposal by the CIT(A). In genuine hardship or prima facie illegal assessments, higher forums can grant complete stay without pre-deposit.

An appeal before the Commissioner of Income Tax (Appeals) must be filed electronically in Form 35 within 30 days from the date of service of the assessment order. An appeal before the Income Tax Appellate Tribunal (ITAT) must be filed in Form 36 within 60 days of receiving the CIT(A) order. In GST matters, appeal before the Appellate Authority must be filed in Form GST APL-01 within 3 months.

Under Faceless Assessment (NeAC), all submissions, evidence, and written rebuttals are submitted digitally through the IT e-filing portal. If an adverse variation to your returned income is proposed in a Show Cause Notice, you are entitled to request an oral hearing conducted via secure video conferencing. Our litigation team prepares the digital paper-book and argues your case during these scheduled video hearings.

Under binding CBDT circulars and affirmed by the Supreme Court of India, any notice, order, or statutory communication issued by the Income Tax Department without a system-generated Document Identification Number (DIN) is treated as invalid and void ab initio (having never existed in law), providing a strong preliminary ground for quashing the proceeding.